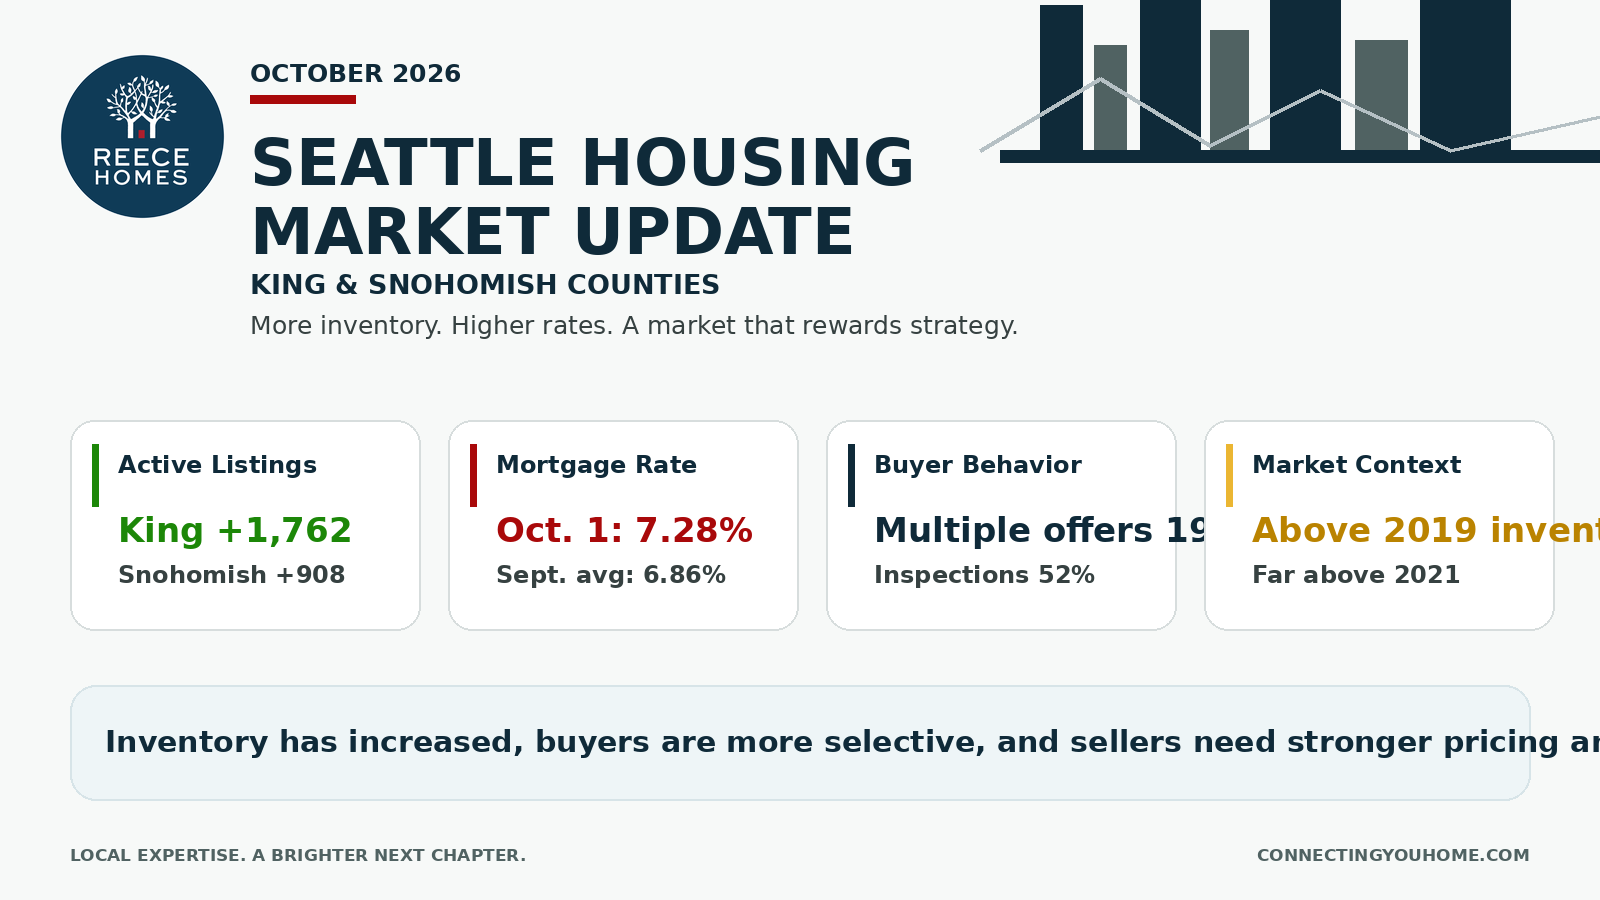
More inventory, higher rates, and a market that rewards strategy.
The latest King and Snohomish County housing data shows a market that continues to move toward balance.
Inventory is significantly higher than last year. Homes are taking longer to sell. Buyers have more choices. Mortgage rates remain elevated. And while prices remain historically strong compared with pre-pandemic levels, the market is more selective than it was during the low-inventory years.
Today’s market is no longer behaving like the ultra-tight 2021 market. It is also not simply returning to 2019. Instead, we are seeing a new version of balance: higher inventory, higher borrowing costs, more buyer selectivity, and continued long-term support for well-positioned homes.
The headline is inventory.
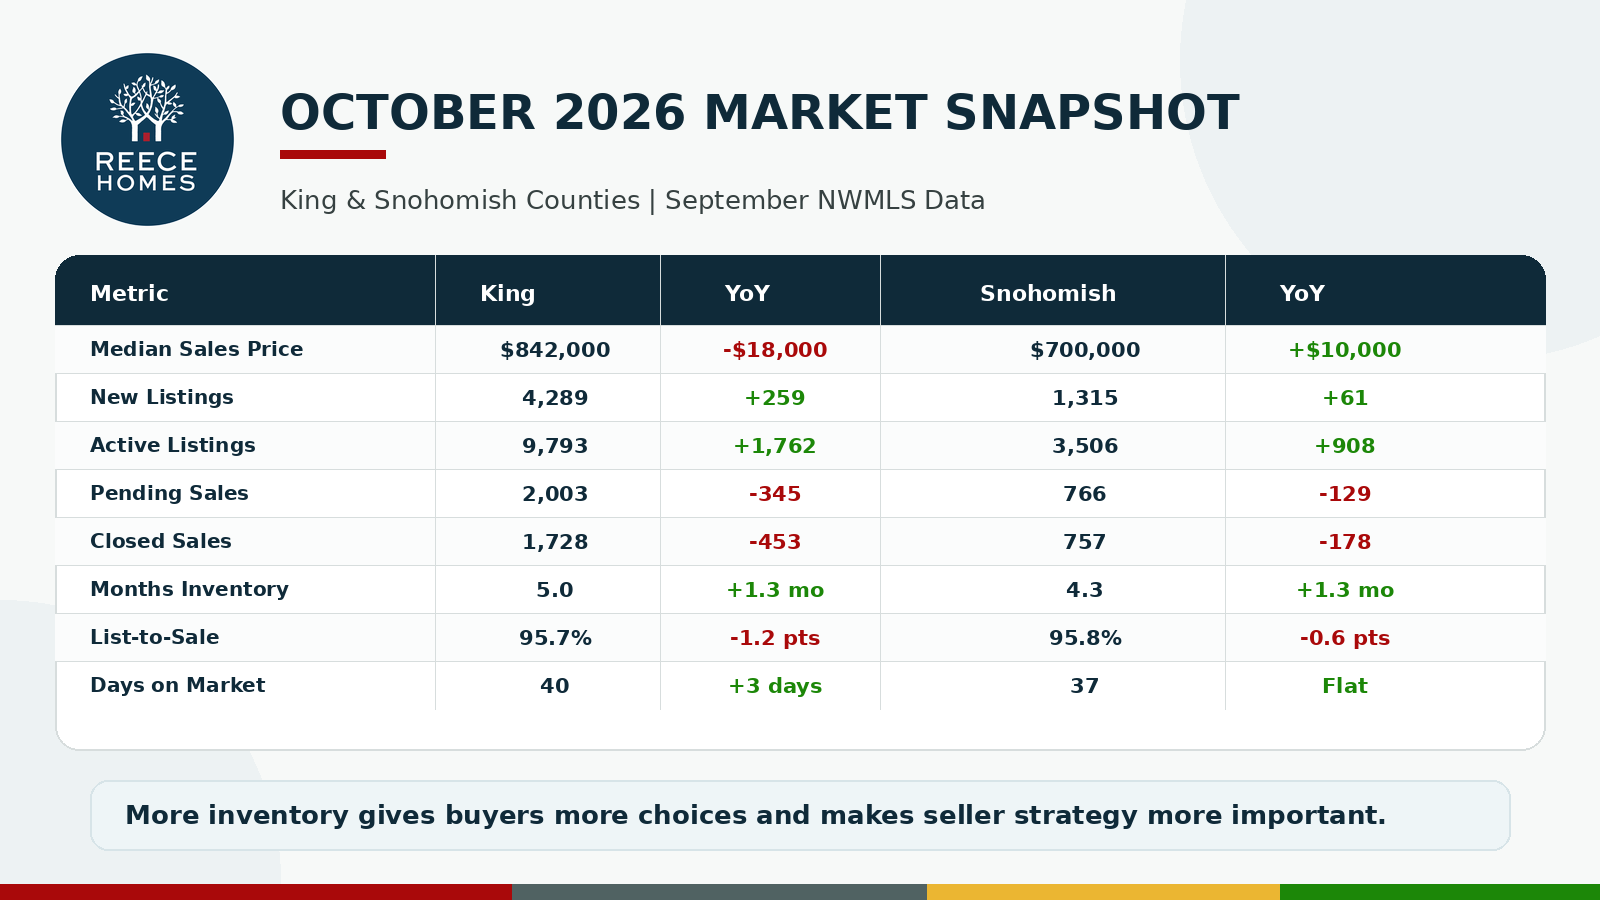
Compared with September 2025, King County had 1,762 more active listings, while Snohomish County had 908 more active listings.
That gives buyers more room to compare homes, evaluate options, and negotiate thoughtfully. It also means sellers need to be more intentional about pricing, preparation, and presentation.
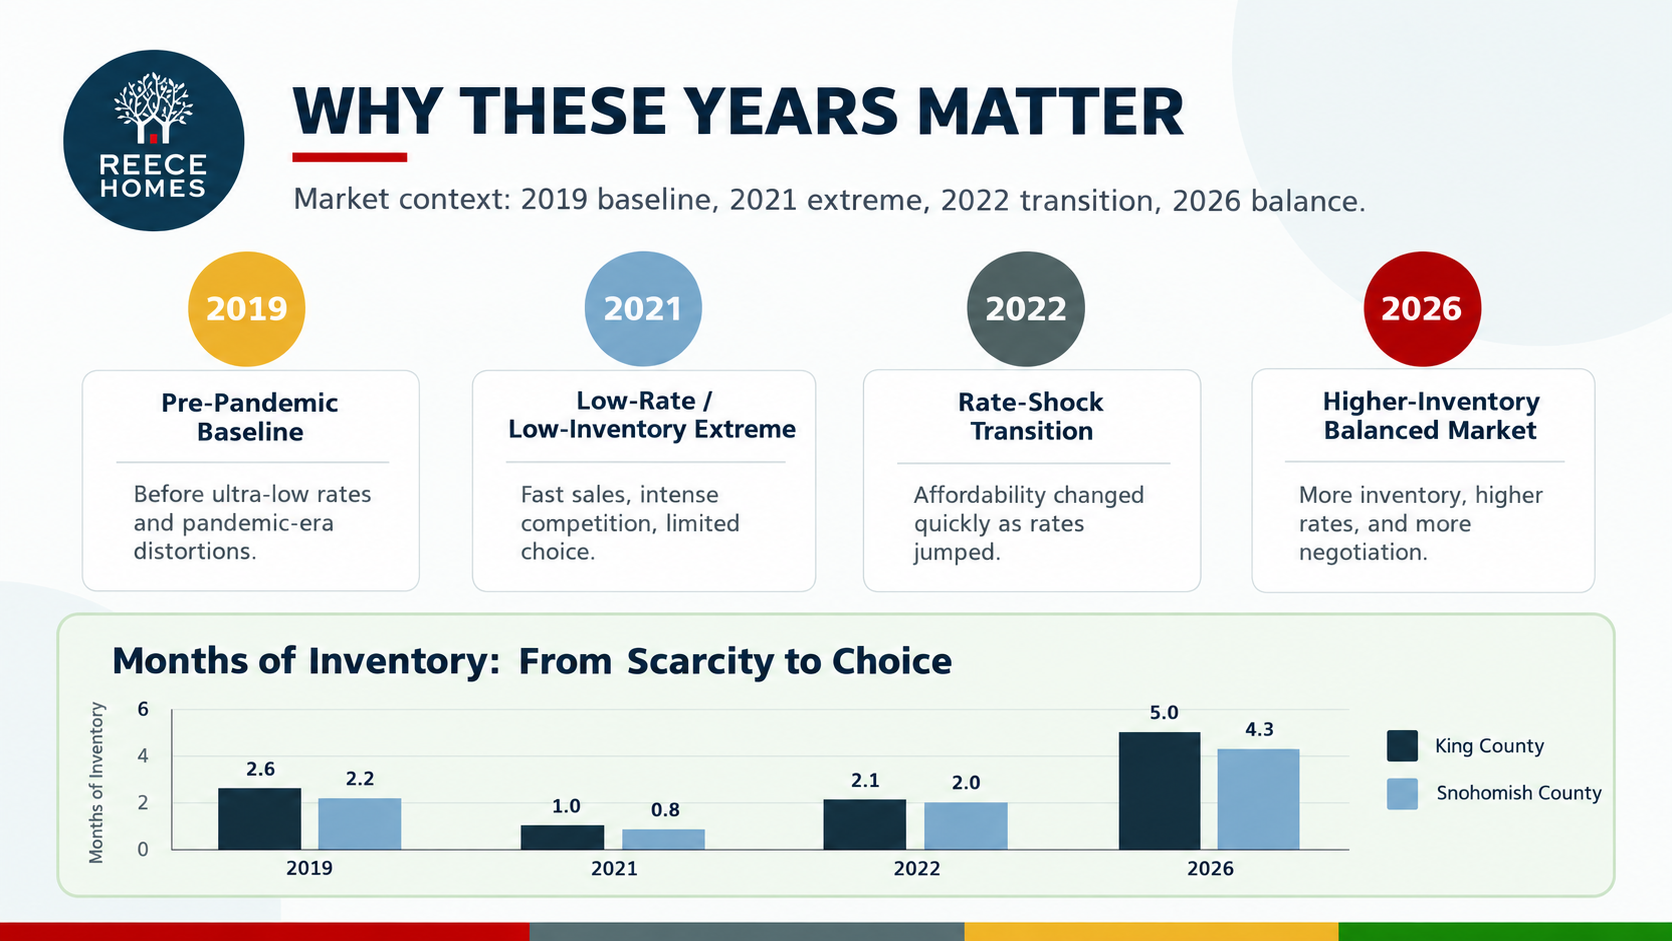
Why We Compare Today With 2019, 2021, and 2022
To understand today’s market, it helps to compare it with three important reference points.
2019
Pre-pandemic baseline. This gives us a useful look at the market before ultra-low mortgage rates, remote-work migration, pandemic-era urgency, and the severe 2021–2022 inventory shortage.
2021
Low-rate, low-inventory extreme. Mortgage rates were historically low, inventory was extremely tight, buyer competition was intense, and homes often sold quickly with multiple offers.
2022
Rate-shock transition. Mortgage rates rose sharply, affordability changed quickly, and the market started adjusting from the low-rate environment into the higher-rate market we are still navigating today.
Today’s market is best understood by comparing it to all three. It has more inventory than 2019, much more inventory than 2021, and a very different rate environment than all of them.
Inventory Is No Longer Tight
The most important shift in today’s market is supply.
In September 2021, King County had 3,303 active listings. In September 2026, it had 9,793.
Snohomish County shows a similar pattern. In September 2021, Snohomish County had 1,179 active listings. In September 2026, it had 3,506.
Active Listings Compared With 2022
| County | Sept. 2022 Active Listings | Sept. 2026 Active Listings | Change |
|---|---|---|---|
| King County | 5,563 | 9,793 | +4,230 |
| Snohomish County | 2,221 | 3,506 | +1,285 |
Active Listings Compared With 2019
| County | Sept. 2019 Active Listings | Sept. 2026 Active Listings | Change |
|---|---|---|---|
| King County | 6,942 | 9,793 | +2,851 |
| Snohomish County | 2,647 | 3,506 | +859 |
That is the clearest evidence that buyers have options again. The market is no longer defined by scarcity in the way it was during 2021 and early 2022.
Months of Inventory Shows the Same Shift
Months of inventory gives us another way to understand the change.
| Month | King County Months of Inventory | Snohomish County Months of Inventory |
|---|---|---|
| Sept. 2019 | 2.6 | 2.2 |
| Sept. 2021 | 1.0 | 0.8 |
| Sept. 2022 | 2.1 | 2.0 |
| Sept. 2026 | 5.0 | 4.3 |
This is a very different supply environment. In 2021, buyers often had to make fast decisions because there simply were not many homes available.
In 2026, buyers have more options, and that changes how they evaluate homes, pricing, condition, and offer terms.
Prices Are Mixed, But Still Historically Strong
Median prices moved differently by county.
Down $18,000 from September 2025.
Up $10,000 from September 2025.
Month over month, King County’s median price increased $5,000, while Snohomish County was unchanged. That tells us the market is not moving uniformly.
Some price points and neighborhoods are holding up better than others. But buyers remain price sensitive, especially when monthly payments are affected by elevated mortgage rates.
Historical context matters here too.
King County’s median price increased from $590,000 to $842,000, up about 42.7%.
Snohomish County’s median price increased from $465,180 to $700,000, up about 50.5%.
So while price growth has cooled and parts of the market have softened, today’s values remain well above the pre-pandemic baseline.
For many homeowners, equity remains strong. For many buyers, affordability remains challenging. Both things can be true at the same time.
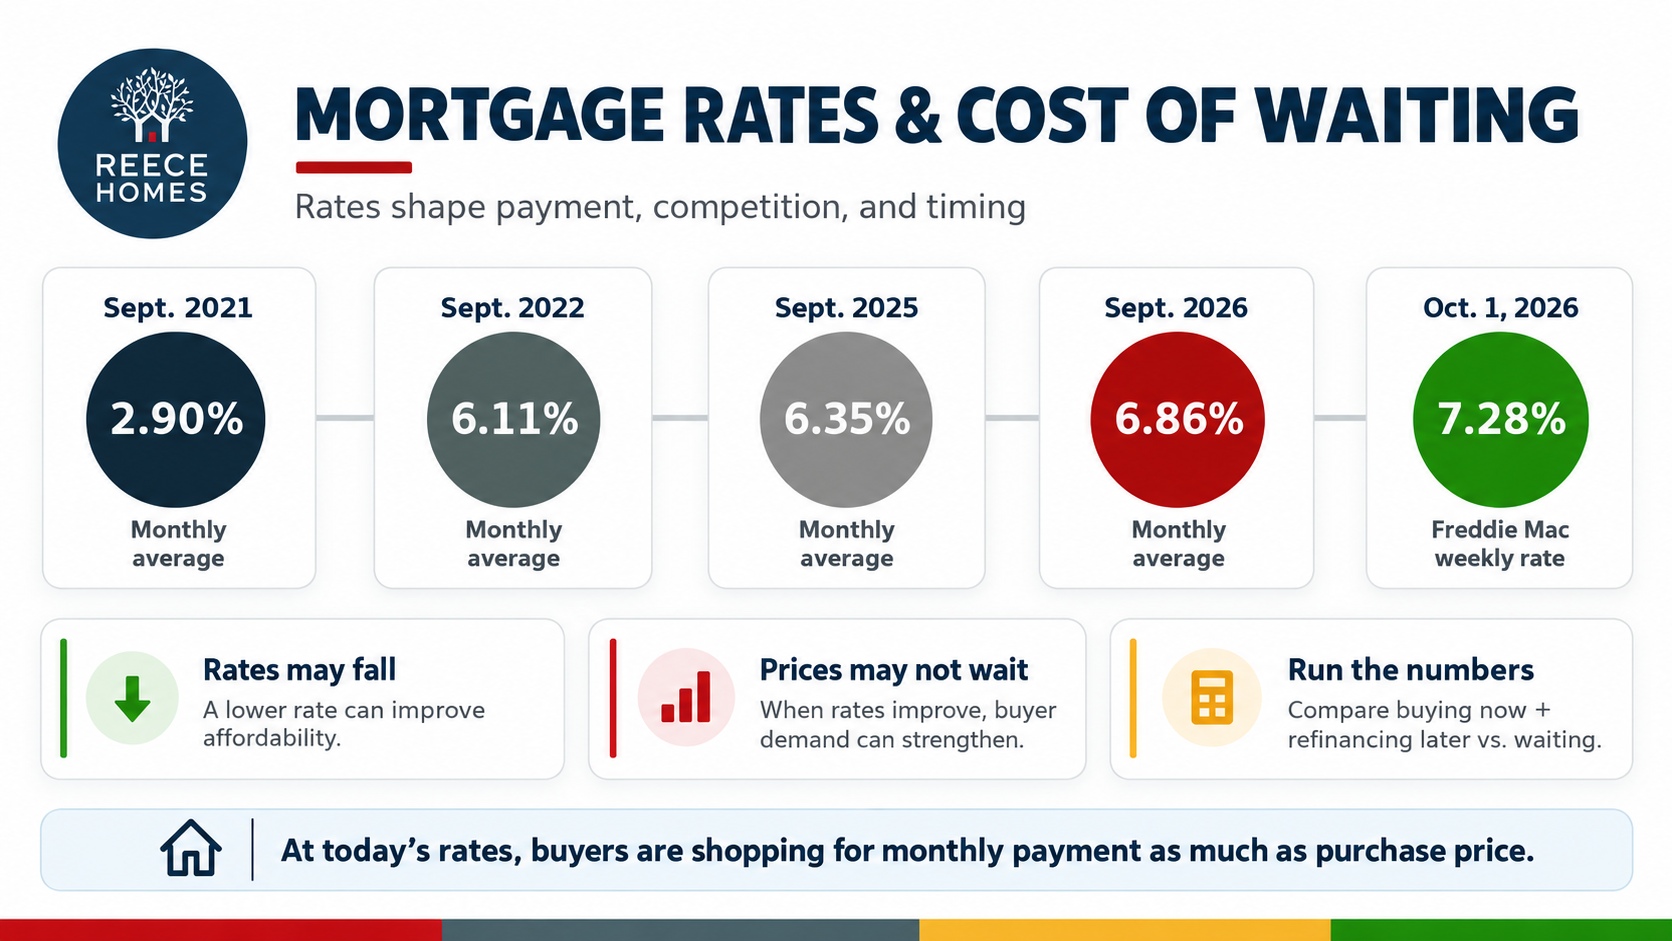
Mortgage Rates Are Reshaping the Market
Mortgage rates remain one of the biggest forces shaping buyer behavior.
The average 30-year mortgage rate was approximately 6.86% in September 2026. That is higher than September 2025, when the average was approximately 6.35%, and dramatically higher than the rate environment buyers experienced in 2021.
As of October 1, 2026, Freddie Mac reported the average 30-year fixed-rate mortgage at 7.28%, up from 7.03% the prior week. Source: Freddie Mac
| Period | Average 30-Year Mortgage Rate |
|---|---|
| Sept. 2021 | 2.90% |
| Sept. 2022 | 6.11% |
| Sept. 2025 | 6.35% |
| Sept. 2026 | 6.86% |
| Oct. 1, 2026 | 7.28% |
A buyer at 7.28% is not just shopping for a home price. They are shopping for a monthly payment.
- Affordability
- Price sensitivity
- Buyer confidence
- Offer strategy
- Inspection decisions
- Requests for seller credits
- Interest in rate buydowns
- Willingness to stretch for a home
Should Buyers Wait for Lower Rates?
With mortgage rates back above 7%, it is natural for buyers to wonder whether they should wait.
The answer depends on the buyer’s budget, timeline, and confidence in where prices and rates go next. But history gives us useful context.
In our article “Do Home Prices Fall When Rates Spike?”, we looked back at prior periods when mortgage rates jumped more than 0.5% within six months and reviewed what happened to Seattle-area home prices afterward. The key takeaway was that higher rates often slow activity, but they do not automatically lead to lower home prices.
We also explored a similar dynamic in “Lessons from 2023.” In 2023, many buyers waited for lower rates. Rates eventually eased, but prices did not wait with them. When affordability improved, buyer demand strengthened, and prices moved higher.
That is why the decision is not simply “buy now” or “wait.” It is a math problem.
Our updated Cost of Waiting Calculator helps buyers compare buying now and refinancing later against waiting for a lower rate.
Broader Economic Context: Rates, Jobs, Inflation, and Local Affordability
The broader economic backdrop remains mixed.
Mortgage rates averaged about 6.86% in September 2026, keeping affordability under pressure.
National unemployment was 4.2% in September. The latest available local data in the economic dashboard showed Seattle-area unemployment at 4.9% and Washington unemployment at 4.9% in August.
Seattle-area inflation, based on the latest local CPI reading in the dashboard, was approximately 4.4% year over year in August.
That matters because buyers are not only responding to mortgage rates. They are also responding to the broader cost of living.
Housing affordability remains challenging. At the same time, the Puget Sound region continues to benefit from high household incomes, long-term employment strength, and limited housing supply in many desirable neighborhoods.
That combination helps explain why prices remain historically strong compared with pre-pandemic levels, even as inventory rises and buyers become more selective.
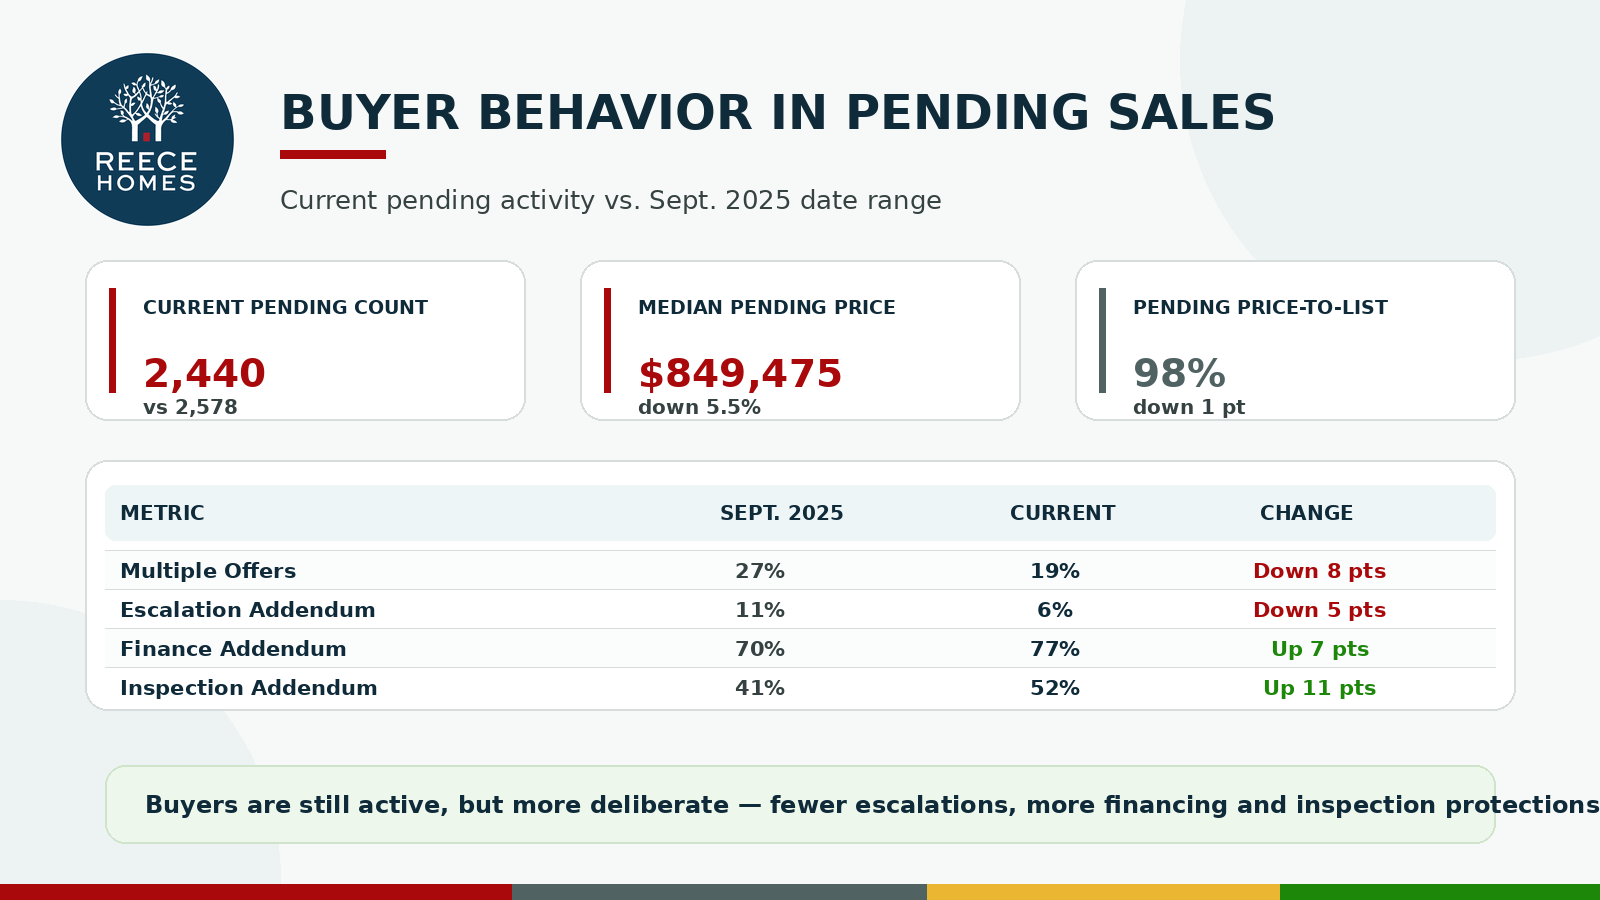
Pending Sales: Buyers Are Active, But More Deliberate
The newest NWMLS Pending Listing Report gives us a better look at what buyers are doing right now.
The report was generated on October 5, 2026 and compares current pending activity with the September 1–30, 2025 date range for residential properties in King and Snohomish counties.
| Pending Metric | Sept. 2025 Date Range | Current Pending | Change |
|---|---|---|---|
| Pending Count | 2,578 | 2,440 | -138 |
| Median Unpublished Pending Price | $898,499 | $849,475 | -5.5% |
| Avg. Pending Price-to-List Ratio | 99% | 98% | -1 pt |
| Multiple Offers | 27% | 19% | -8 pts |
| Escalation Addendum | 11% | 6% | -5 pts |
| Finance Addendum | 70% | 77% | +7 pts |
| Inspection Addendum | 41% | 52% | +11 pts |
This is one of the clearest signs of a more deliberate market.
Buyers are still active, but they are behaving differently than they were a year ago. There are fewer current pending listings than in the September 2025 comparison period, the median unpublished pending price is lower, and the average pending price-to-list ratio has softened from 99% to 98%.
The buyer behavior metrics are especially important. Multiple-offer activity dropped from 27% to 19%, and escalation addenda dropped from 11% to 6%. At the same time, finance addenda increased from 70% to 77%, and inspection addenda increased from 41% to 52%.
For sellers, this means pricing and preparation matter more. For buyers, it means there may be more room to negotiate and preserve important protections, especially on homes that have been sitting, need work, or were priced too aggressively at launch.
Closed Sales Slowed
Closed sales were lower than last year in both counties.
- King County closed sales were down 453 from September 2025.
- Snohomish County closed sales were down 178 from September 2025.
This is one of the clearest signs that the market has slowed from the pace of prior years.
More homes are available, but not every listing is converting into a sale. Buyers are comparing more carefully, watching payment levels, and responding most strongly to homes that are priced and presented well.
Homes Are Taking Longer To Sell
Market time continues to increase.
- King County homes averaged 40 days on market, up 3 days from last year.
- Snohomish County homes averaged 37 days on market, unchanged from last year.
The historical comparison is more striking.
In September 2021, King County homes averaged 16 days on market, while Snohomish County homes averaged 12 days. In September 2022, King County averaged 26 days and Snohomish County averaged 27 days.
Today’s market is slower. That does not mean homes are not selling. It means the pace has changed.
Buyers are taking more time. Sellers are facing more competition. And the first few weeks on market are increasingly important.
List-to-Sale Ratios Are Softer
Both counties are also seeing softer list-to-sale ratios.
- King County list-to-sale ratio was 95.7%, down 1.2 percentage points from last year.
- Snohomish County list-to-sale ratio was 95.8%, down 0.6 percentage points from last year.
That is dramatically different from September 2021, when both counties were above 102%.
This is another sign that buyers are negotiating more. For sellers, list price needs to be strategic from the start.
What This Means for Sellers
Sellers still have opportunity, but the market is less forgiving.
The homes that perform best are typically the ones that are:
- Priced accurately from day one
- Prepared before going live
- Easy for buyers to understand
- Professionally photographed and marketed
- Positioned clearly against competing listings
- Responsive to buyer feedback
The biggest mistake sellers can make right now is assuming that last year’s strategy will work in this year’s market.
What This Means for Buyers
Buyers have more leverage than they have had in several years.
More inventory can create:
- More homes to choose from
- Less pressure to rush
- Better ability to keep important protections
- More room to negotiate price, repairs, credits, or terms
- Better odds of finding a home that fits both lifestyle and budget
The bigger question is not only whether rates might come down later. It is whether the combination of price, rate, inventory, and competition is better today than it may be later.
That is why running the numbers matters.
What This Means for Investors
For investors, rising inventory can create more opportunities, but higher rates continue to make the numbers more challenging.
The best opportunities may come from properties where the average buyer sees friction, such as:
- Cosmetic updates
- Longer days on market
- ADU or DADU potential
- Strong rental locations
- Properties that were overpriced initially
- Sellers who value certainty and clean terms
This is not a market where every deal works. But it is a market where disciplined investors may find opportunities that were harder to find when inventory was extremely low.
What We’re Watching Next
- Whether inventory remains elevated through fall
- Whether mortgage rates stay above 7%
- Whether pending sales stabilize
- Whether sellers adjust pricing expectations
- Whether days on market continue increasing
- Whether buyer protections remain more common
- Whether buyers re-enter quickly if rates improve
The fall market will be important.
If inventory remains elevated and buyer activity slows further, sellers may need to become more flexible. If rates improve or buyers gain confidence, some of the current inventory could create opportunity for renewed activity.