Published October 1, 2026
Today Looks a Lot Like 2023. Here's What Happened Next.
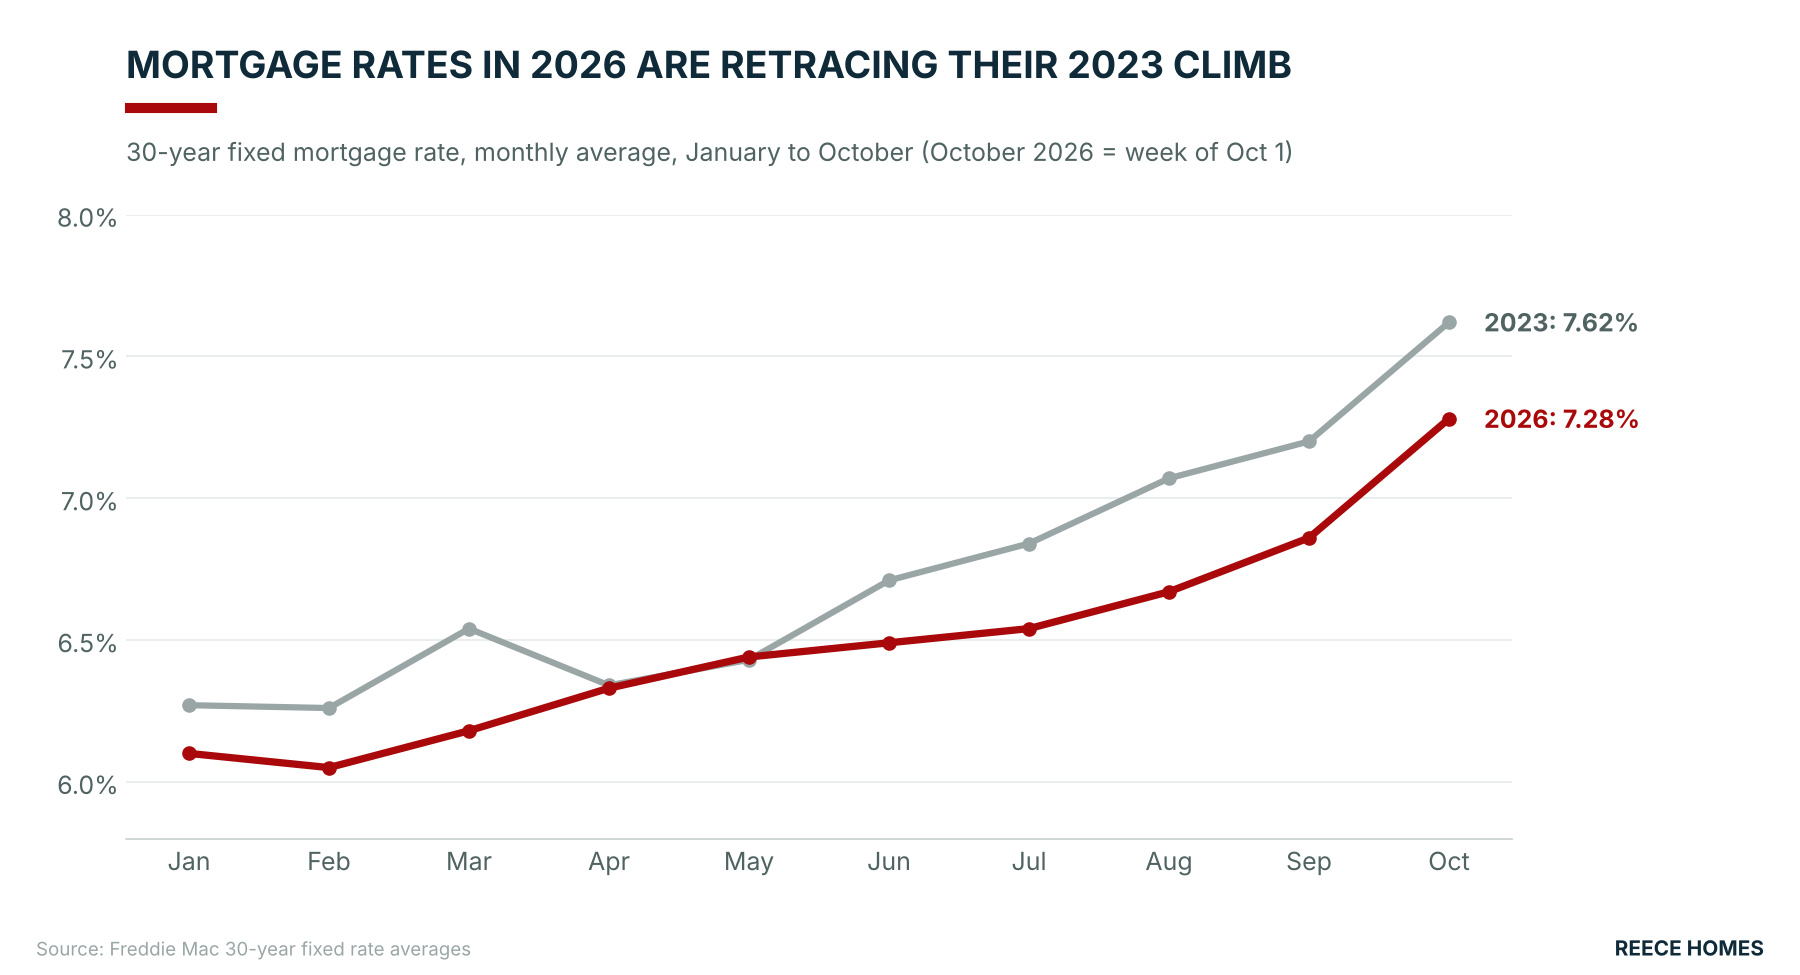
Mortgage rates just crossed 7% again. Freddie Mac's 30-year average hit 7.28% this week, up from about 6% in February. If you're shopping for a home in King or Snohomish County, the natural instinct is to pause and wait for rates to come back down.
We've seen this exact moment before. In the fall of 2023, rates climbed past 7% and many buyers decided to sit it out. What happened over the next few months is the best guide we have for what could happen next, and it's worth knowing before you decide to wait.
Then and now
This year's rate climb is tracing 2023's almost month for month: a low near 6% in late winter, then a steady rise past 7% by fall.
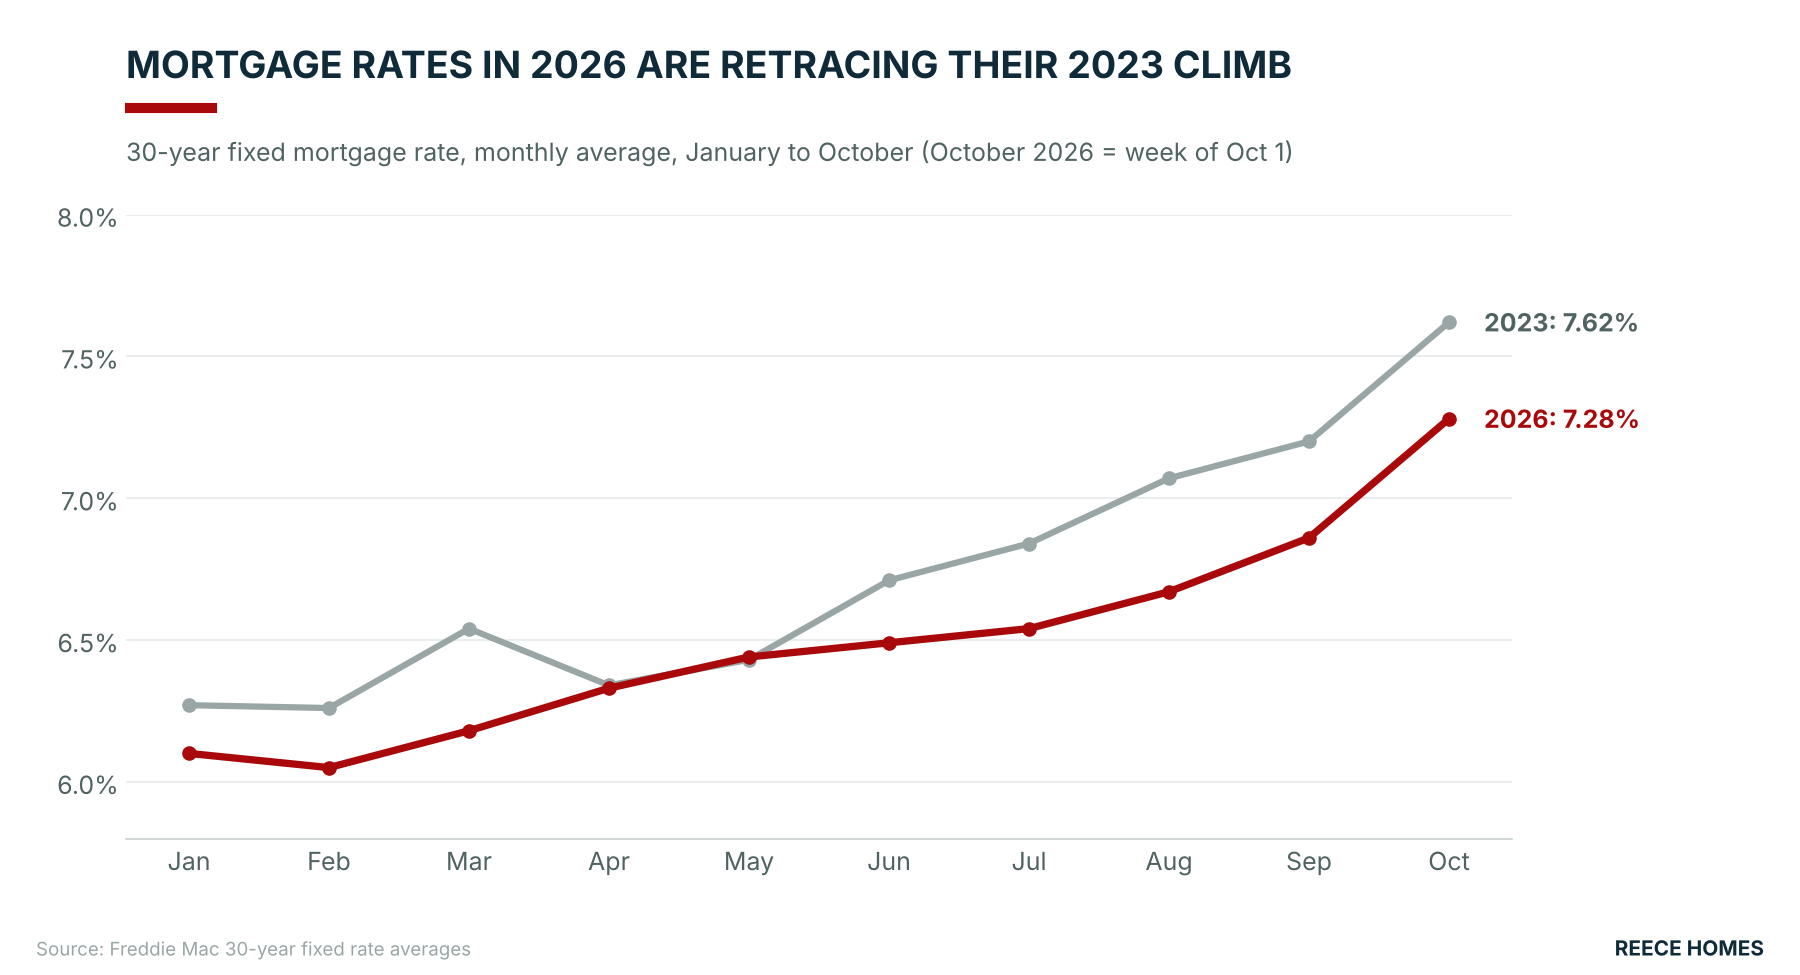
The big difference is what buyers find when they go shopping. In 2023, inventory was tight. Today, buyers have far more choice.
| King County | September 2023 | September 2026 |
|---|---|---|
| 30-year rate (early October) | 7.62% | 7.28% |
| Median sale price | $775,000 | $842,500 |
| Months of inventory | 2.3 | 5.1 |
| Average days on market | 26 | 40 |
| Sale price vs. original list price | 98.2% | 95.7% |
What happened when rates dropped in late 2023
Rates peaked at 7.62% in October 2023 and fell a full point within three months. Prices didn't wait.
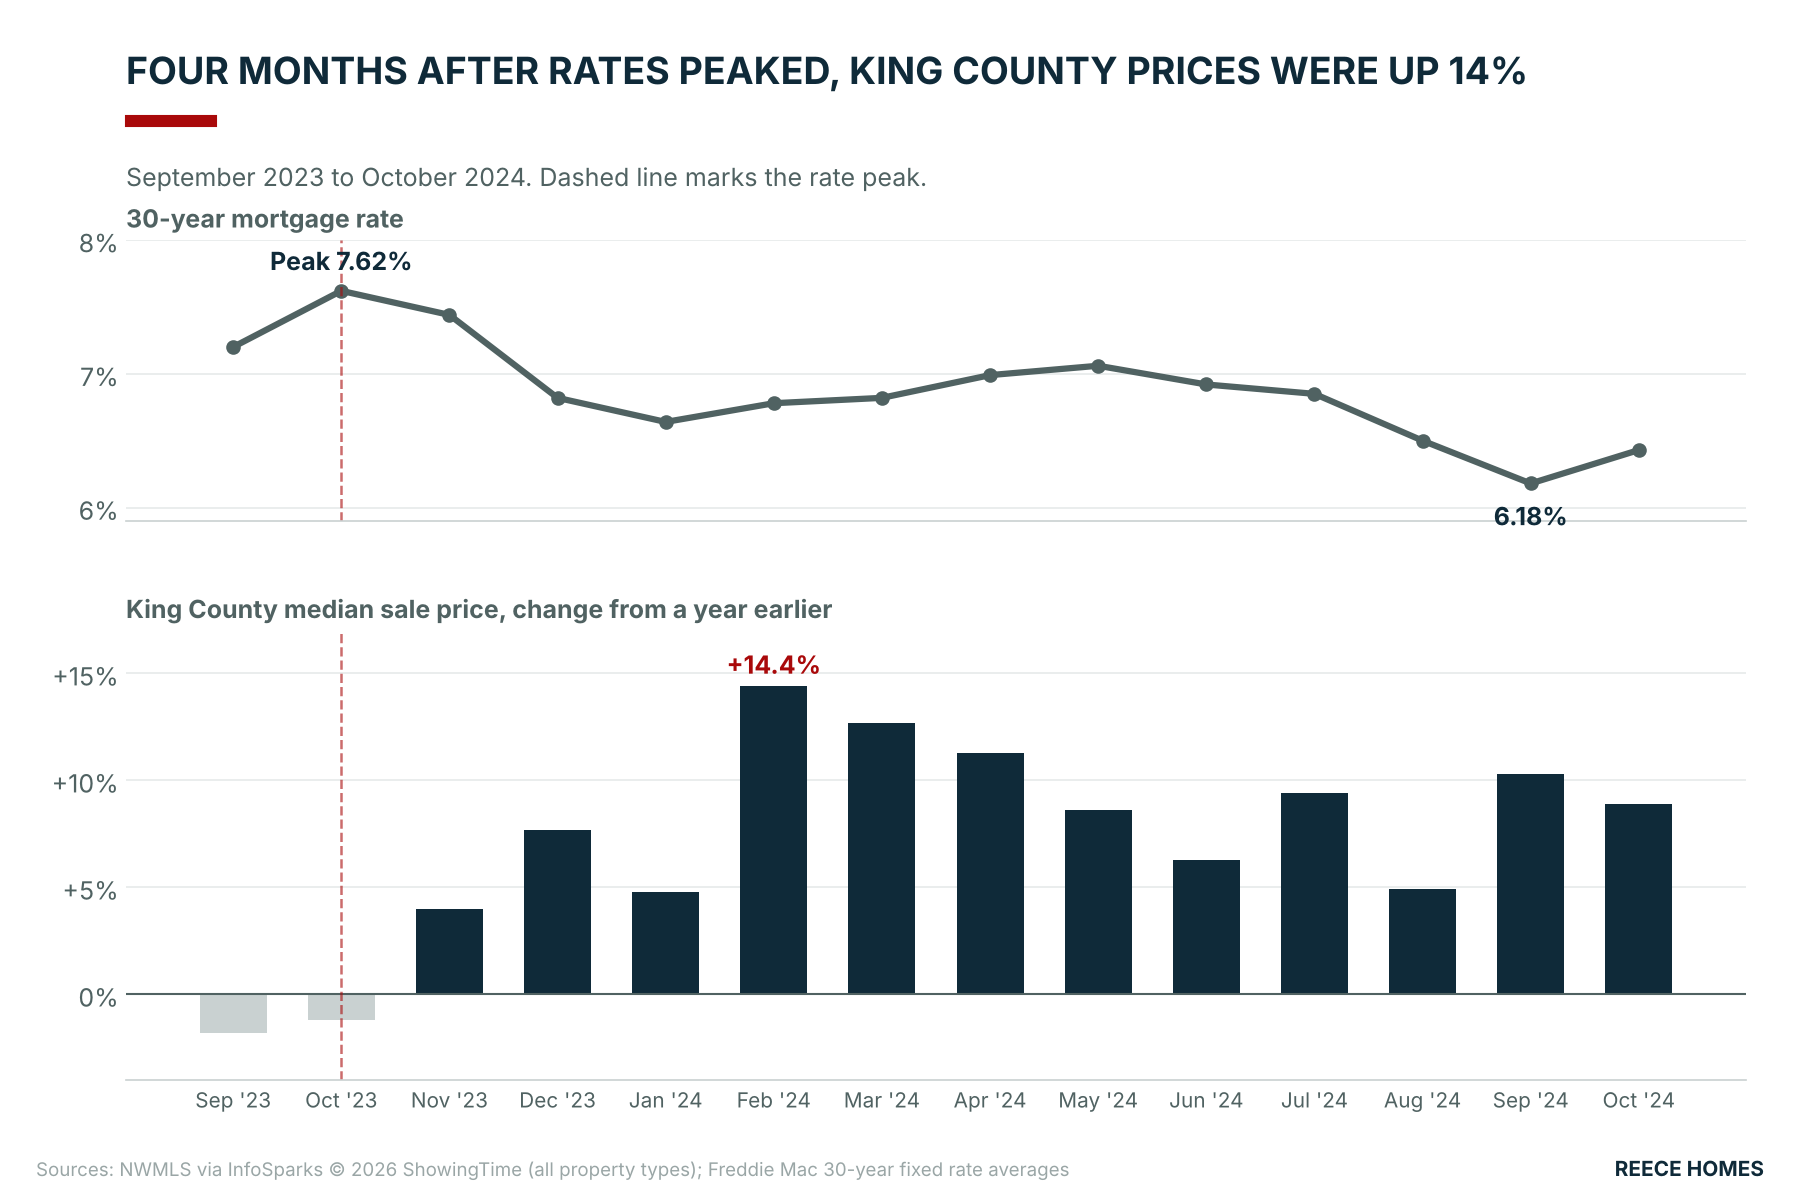
In October 2023, the King County median was $790,000 and slightly below the year before. By April 2024 it was $873,790, up 10.6% in six months. In a typical year, prices rise only about 2–5% over that same October-to-April stretch.
Notice that rates in the spring of 2024 were still close to 7%. Buyers didn't need rates to fall to 6% to come back. A one-point drop from the peak was enough.
Why so many buyers missed the window
The trouble with waiting for lower rates is that every other buyer is waiting for the same thing. When rates finally drop, everyone who was on the sidelines comes back at once.
- Competition returned fast. King County pending sales were up 13% year over year by December 2023, just two months after the rate peak.
- Homes stopped negotiating. By April 2024, King County homes were selling at 102.6% of list price on average, versus 99.8% in October 2023. Average market time fell from 45 days in January to 20 days by April.
- Sellers didn't keep up. Even when more listings came on later in 2024, pending sales grew faster. In September and October 2024, as rates touched 6.18%, King pending sales ran 27–30% ahead of the year before.
By the time a lower rate showed up on the news, the discounts and negotiating room that existed at 7.6% were gone. Waiting buyers got their lower rate, but they paid for it in price and competition.
Buy now and refinance vs. wait: what 2023 actually paid
The buyer who bought at the peak and refinanced later ended up with a lower payment and $57,000 more equity than the buyer who waited. Here are two buyers of a median-priced King County home, each putting 20% down.
- Buyer A bought in October 2023 at $790,000 with a 7.62% rate, then refinanced 11 months later when rates hit 6.18%.
- Buyer B waited for that same 6.18% rate and bought in September 2024, when the median was $854,950.
| September 2024 | Buyer A: bought, then refinanced | Buyer B: waited |
|---|---|---|
| Purchase price | $790,000 | $854,950 |
| Down payment | $158,000 | $170,990 |
| Loan balance | $626,800 | $683,960 |
| Monthly payment (principal & interest) at 6.18% | $3,831 | $4,180 |
| Home equity | $228,150 | $170,990 |
Buyer B got the rate they wanted, but paid $64,950 more for the same home, needed $12,990 more cash at closing, and still pays $349 more every month. Buyer A carried a higher payment for 11 months and paid refinance closing costs, but came out well ahead.
The key insight: you can change your rate later, but you can never change your purchase price.
To be fair: falling rates don't always mean rising prices
Not every rate drop sets off a rush. Through 2025 and early 2026, rates slid gradually from about 7% to 6%, and King County prices stayed roughly flat while Snohomish County prices dipped. Seattle-area unemployment rose from 4.3% to 5.4% over that stretch, and buyers stayed cautious.
The pattern in our data is this: sharp rate drops after a peak have brought buyers back quickly; slow drifts during job worries have not. Nobody can promise which one comes next, which is exactly why timing the market is so hard.
One thing is different today, and it works in your favor. King County has 5.1 months of inventory, the most since early 2012, versus 2.3 months in September 2023. Homes are averaging 40 days on market and selling for 95.7% of their original list price. Buyers today have more choice and more negotiating room than they did in 2023. If the 2023 pattern repeats, that leverage is what disappears first.
Run your own numbers
Every buyer's situation is different: your price range, down payment, rent and timeline all change the answer. Our Wait for Rates, or Buy Now? calculator lets you plug in your own assumptions and see how buying now and refinancing compares with waiting. Try the calculator
If you'd like to talk it through, the Reece Homes team can run the numbers with you and a trusted lender, and help you use today's negotiating room while it lasts. Contact us
Sources: Northwest Multiple Listing Service® via InfoSparks © 2026 ShowingTime, all property types, through September 2026; Freddie Mac 30-year fixed mortgage rate averages; U.S. Bureau of Labor Statistics via FRED. Examples are illustrative, use median prices, and show principal and interest only. This is not financial advice; future rates and prices may differ.